- Home
- Real Estate Services in Davao
- Home Loan Assistance Davao
Home Loan Assistance in Davao
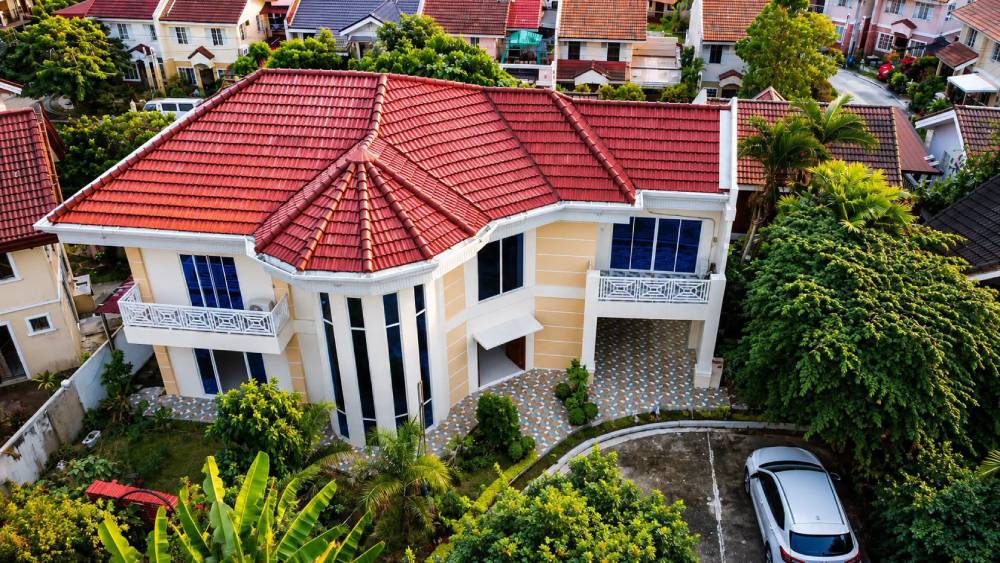
Buying a home is an exciting milestone, but arranging the financing can feel complicated. Different lenders have different requirements, documents must be accurate and complete, and the property itself must pass legal and appraisal checks. A missing signature, outdated certificate, unclear title entry, or incomplete proof of income can slow the process and place your planned purchase at risk.
Davao Property Solutions provides professional Home Loan Assistance Davao buyers can rely on when preparing for a property purchase. We help clients understand the financing process, organize the required documents, coordinate property-related requirements, and monitor the application from the initial assessment through approval and loan release.
Whether you are buying your first house, upgrading to a larger family home, investing in a condominium, or purchasing a residential lot with plans to build, our team can help you approach financing with better preparation and fewer surprises.
A Simple Home Loan Process for Davao Buyers
Although exact procedures vary, a typical transaction follows these stages:
Consultation and goal setting – Define your budget, target property, timeline, and financing needs.
Financial readiness review – Assess income documents, existing obligations, available down payment, and other costs.
Financing route and property selection – Identify a suitable lender or program and match it with an eligible property.
Document preparation – Complete borrower, income, seller, and property requirements.
Application submission – File the application through the proper channel and obtain proof or confirmation of submission.
Credit evaluation and appraisal – The lender reviews the borrower’s capacity and evaluates the property.
Additional compliance – Respond to clarifications or supply updated documents when requested.
Approval and signing – Review the approved amount, rate, term, monthly payment, fees, and conditions before signing.
Mortgage and release requirements – Complete insurance, title, annotation, and other pre-release conditions.
Loan release and property turnover – Coordinate payment to the seller and complete the remaining transfer or turnover steps.
Preparation is the best way to prevent avoidable delays. Starting early gives you time to correct inconsistencies and request documents that may take several days or weeks to obtain.
Why Choose Davao Property Solutions for Pag-ibig Housing Loan Processing?
- Expertise and Experience:
With our in-depth knowledge and experience in Pag-ibig housing loan processing, we are equipped to handle the complexities of the process. Our team stays updated with the latest guidelines and regulations, ensuring accurate and reliable services. - Personalized Approach:
We understand that each client’s situation is unique. That’s why we offer personalized assistance tailored to your specific needs and requirements. We take the time to understand your goals and provide solutions that best suit your circumstances. - Efficiency and Timeliness:
We value your time and strive for efficiency throughout the loan processing journey. Our dedicated team ensures that all tasks are completed promptly, minimizing any potential delays in the process. - Transparent Communication:
We believe in open and transparent communication with our clients. You can expect regular updates on the
Frequently Asked Questions (FAQs) for Home Loan Assistance Davao
What is Home Loan Assistance Davao?
It is a support service that helps a buyer understand financing options, prepare borrower and property documents, coordinate appraisal requirements, monitor the application, and manage steps leading to approval and release.
Does Davao Property Solutions guarantee loan approval?
No. Only the lender can approve or deny an application. We improve preparation and coordination, but approval depends on the borrower’s qualifications, credit evaluation, property acceptability, appraisal, and the lender’s rules.
Can you help with both Pag-IBIG and bank housing loans?
Yes. We can provide process and document assistance for common home-financing routes applicable to the property. Requirements and final decisions come from the selected institution.
What properties can usually be financed?
Depending on the lender and program, financing may apply to a house and lot, townhouse, condominium unit, residential lot, home construction, or property improvement. The property must meet the chosen lender’s legal, technical, and appraisal standards.
How much can I borrow?
The amount depends on factors such as verified income, existing obligations, age, repayment term, appraised property value, down payment, credit assessment, and lender policy. An advertised maximum is not an automatic entitlement.
How long does home loan processing take?
There is no single guaranteed timeline. Processing depends on the lender, completeness of documents, appraisal schedule, property issues, credit evaluation, and how quickly the parties satisfy additional conditions.
Can a self-employed applicant qualify?
Yes, subject to lender evaluation. Self-employed applicants commonly need business registration, permits, tax returns, bank statements, financial records, and evidence showing stable and sufficient income.
Can an OFW apply for a home loan in Davao?
Yes, many financing institutions accept qualified OFW applicants. Requirements may include employment or agency records, proof of remittances, overseas income documents, identification, and properly executed authority for a representative when applicable.
Can spouses or family members combine their income?
Some lenders allow a spouse or qualified co-borrower, subject to their rules. All applicants may need to submit identity, income, and credit documents and may share responsibility for the loan.
What if the property's appraised value is lower than the selling price?
The buyer may need a larger cash contribution. Other possible responses include negotiating the price, reconsidering the transaction, or choosing another property. The options depend on the contract and lender’s policy.
Should I get pre-qualified before choosing a home?
An early assessment is helpful because it gives you a more realistic target budget. However, pre-qualification or preliminary assessment is not the same as final loan approval, particularly before the property has been evaluated.
What costs should I prepare aside from the down payment?
Possible costs include reservation charges, appraisal, processing, insurance, notarial fees, taxes, registration, title transfer, and other lender or transaction expenses. Request a written estimate because the responsible party and amount can vary.
What causes home loan delays?
Common causes include incomplete income records, inconsistent personal information, outdated property documents, title concerns, appraisal access problems, slow seller compliance, and delayed responses to additional lender requirements.
Can you help if I already found a property?
Yes. We can review where you are in the process, help identify financing-related property requirements, organize documents, and assist with coordination. Any existing reservation or sale agreement should also be reviewed carefully for deadlines and conditions.
Can you help me find a property that fits my loan budget?
Yes. Davao Property Solutions can help connect your realistic financing range with available property options in Davao, subject to availability, seller terms, and lender eligibility.